

Feenko: Subscription Manager
4.4

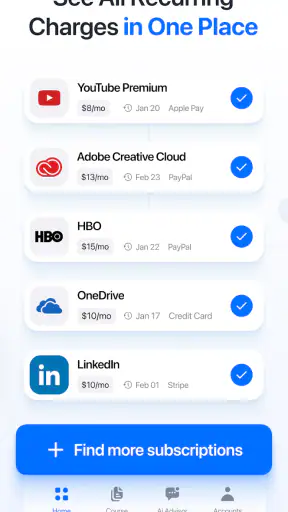
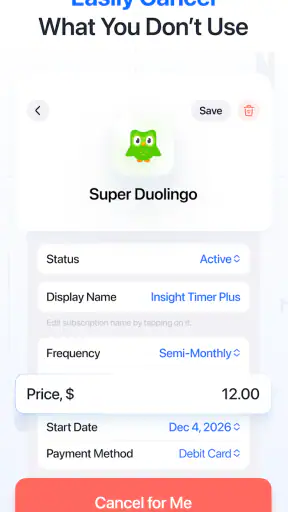
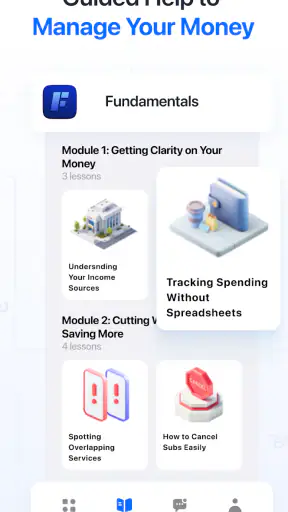
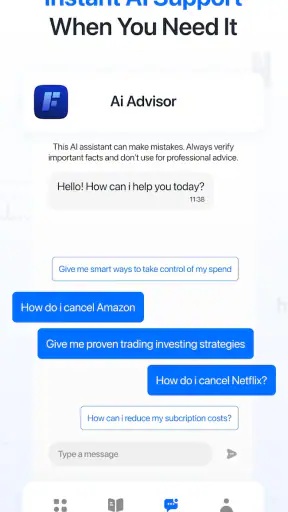
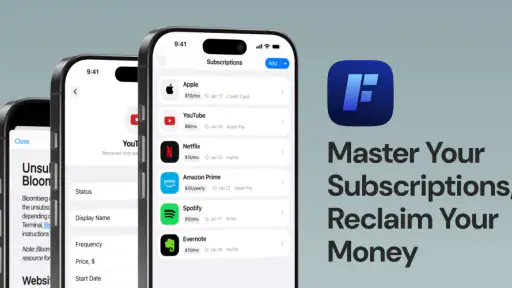
I approached Feenko: Subscription Manager as a practical finance app rather than something I would open for entertainment. The main question for me was simple: can it make recurring spending easier to understand and manage without turning a small household task into another chore? That is the standard I would use before recommending it to a friend.
My experience suggests that Feenko is most interesting for people who regularly lose track of subscriptions, forget renewal dates, or want a clearer view of recurring commitments. It is free to install, carries an Everyone age rating, and comes from GotYourBack Technologies LTD. The app has reached over 100 thousand installs and holds a 4.4 average from around 2 thousand ratings, which gives it a useful level of public feedback without making popularity the only reason to try it.
How I would decide whether Feenko belongs on my phone
I would begin by identifying the problem I actually want to solve. If I only have one or two recurring services and already check my bank statement carefully, a dedicated subscription manager may not change much. A note, calendar reminder, or spreadsheet could be enough. Feenko becomes more appealing when several small payments are spread across different services and I need one place to think about them.
The important decision is not simply whether the app can display recurring expenses. I would also consider how much setup I am willing to do, whether I want a focused tool instead of a complete budgeting suite, and whether I am comfortable managing financial information inside a specialist app. Those questions matter because convenience is only useful when the routine stays easy after the first setup.
For me, the strongest test is a normal month. I imagine checking a streaming service, a cloud-storage plan, a fitness membership, and a work-related tool. If I can quickly recognize what renews soon, decide what still deserves the money, and avoid paying for something forgotten, the app has earned its place. If reviewing the list takes longer than checking my usual banking app, the benefit becomes much smaller.
Another decision point is the difference between subscription awareness and full financial management. Feenko is positioned around subscriptions, so I would not choose it expecting the breadth of a general budgeting platform. A broad finance app may be better for someone who wants investments, debt planning, detailed categories, and a complete household budget in the same workspace. Feenko makes more sense when recurring commitments are the specific problem.
The first-use experience and the setup trade-off
Subscription tools usually ask users to create a reliable starting picture. That means I would treat the first session as an audit, not a quick download-and-forget moment. I would gather recent statements or receipts, write down the services I know I pay for, and check less obvious renewals such as annual plans or subscriptions purchased through a different platform.
This is one of the less obvious practical points: the quality of the result depends heavily on the quality of the initial inventory. A manager cannot help me notice a forgotten service if I never add it or otherwise bring it into my review routine. I would therefore set aside a quiet few minutes for setup rather than entering information casually between other tasks.
I would also avoid treating every recurring payment as equally urgent. A low-cost service that I use daily is not automatically a problem, while a more expensive plan that I rarely open deserves attention. Feenko is most useful when I use its overview to support decisions, not when I simply collect subscriptions in another list.
That distinction helps answer a question many people have before installing: will the app automatically solve forgotten subscriptions? I would not rely on any manager as a substitute for checking my own accounts and receipts. The sensible workflow is to use Feenko as a central review point, then confirm important changes with the original service or payment provider before cancelling anything.
Where the focused approach works well
The clearest strength is focus. Instead of asking me to build an entire personal-finance system, Feenko addresses a narrow and familiar source of waste: recurring charges that continue quietly. That focus can make the app less intimidating than a full budgeting product, especially for someone who does not want to categorize every purchase.
I can see the value for a user who shares household costs but does not want to merge every financial detail. A couple could use a subscription review as a conversation starter: which services are shared, which belong to one person, and which are still worth keeping? The app would not replace an agreement about who pays, but a visible recurring list can make that conversation more concrete.
It may also suit someone whose income changes from month to month. In that situation, recurring commitments are important because they are harder to ignore than occasional purchases. A subscription review can help separate obligations that arrive automatically from spending that can be adjusted more easily. I would use that distinction when planning a tighter month.
Another useful scenario is moving between phones, banks, or payment cards. The transition itself can expose how many services are attached to old payment details or forgotten accounts. I would use Feenko as a checklist during that process, while still updating each subscription directly. The app can organize my awareness; it should not be treated as proof that every provider has changed successfully.
A realistic everyday routine
Imagine I notice a recurring charge while reviewing my bank activity on a Sunday evening. I recognize the company but cannot remember whether the service is still useful. Instead of making a decision immediately, I would record it in my subscription review, note the next renewal information available to me, and check how often I used the service during the previous month.
That small pause is where a manager can be more valuable than a simple alarm. A calendar reminder might tell me that a payment is approaching, but it does not necessarily encourage a broader review of similar commitments. I would use Feenko to look at the whole recurring picture, then decide whether the service belongs in my regular spending.
If I decide to cancel, I would open the provider’s own account page and complete the cancellation there. I would then return to my subscription records and update them so the list remains trustworthy. This two-step habit is important: removing an entry from a manager is not the same as ending a contract, and confusing those actions could lead to an unwanted renewal.
For a family, I would repeat the review once a month and keep the conversation short. Each person could identify one service they use and one they no longer need. That turns the app into a decision aid rather than a passive archive. The real saving comes from the follow-through, not from installing the application.
Where other categories may fit better
Feenko may not be the right choice for someone who wants every financial activity connected in one place. A full budgeting app is usually the better category for users who need income planning, detailed spending analysis, savings targets, or debt tracking alongside subscriptions. I would avoid choosing a narrow tool and then expecting it to behave like a complete financial dashboard.
A spreadsheet may be preferable for people who want complete control over formulas, custom fields, and long-term records. It requires more manual work, but it can be adapted to unusual household arrangements. I would choose that route if I needed a highly personalized system or wanted to keep my information in a format I already understand well.
Calendar reminders remain a reasonable alternative for a very small number of subscriptions. They are especially suitable when my only concern is remembering a renewal date. The trade-off is that reminders are separate events, so they do not naturally encourage a consolidated review of the entire recurring-cost picture.
Banking tools may also be enough for users who already receive clear recurring-payment alerts. Their advantage is proximity to the actual transaction. Their limitation is that transaction history can be noisy, and a merchant name may not immediately reveal which service, plan, or account created the charge. Feenko’s narrower purpose is more useful when I want a deliberate subscription inventory rather than a general stream of payments.
I would also be cautious if I am looking for automatic certainty. Financial apps differ in how they handle data entry, account connections, reminders, and privacy choices. Feenko’s value for me is strongest when I actively review what I record. Someone who wants a completely hands-off system should compare it with alternatives designed specifically around automation, while checking those products’ own terms and limitations.
Costs, paid options, and the cost of switching
The app is free to download, which lowers the barrier to testing whether its workflow suits me. There are in-app purchases ranging from $0.99 to $39.99 per item, so I would look carefully at what any optional purchase unlocks before committing. I would not assume that paying is necessary for every user, nor would I assume that the free experience covers every need without checking inside the app.
My practical advice is to start with a small, representative inventory. I would add the subscriptions I understand best, use the app during one review cycle, and judge whether it saves time or creates another maintenance task. That approach is better than entering every historical payment immediately, because it lets me evaluate the workflow before investing effort in a full cleanup.
The cost of switching from another method is mostly organizational. Moving from a note or spreadsheet means recreating names, amounts, renewal patterns, and cancellation details. Moving from a broader budgeting app may mean accepting a narrower view of finances. I would keep the old record until I had checked the new one against recent statements, especially for annual charges that are easy to overlook.
There is also a habit cost. If I stop maintaining the list, its usefulness declines. I would choose one recurring review moment, such as the first weekend after receiving regular income, and use it to verify new subscriptions, cancelled services, and upcoming renewals. A short consistent routine is more reliable than a detailed setup that I never revisit.
Version 1.7.48 is the current version, and the app supports Android 7.0 or later. That makes compatibility worth checking before installation on an older device. I would also keep the operating system and the app updated when possible, particularly because finance-related tools deserve sensible attention to maintenance and account security.
Privacy, trust, and sensible financial habits
Because this is a finance app, I would not install it casually on a shared or poorly secured phone. I would use a device lock, avoid recording sensitive information that the app does not need for my personal workflow, and review the app’s own privacy and permission explanations before adding anything confidential. These are habits I would recommend with any financial organizer, not just this one.
I would also separate planning information from authentication information. A subscription manager can help me remember what I pay for, but I would not use it as a place to store passwords, security codes, or complete payment credentials. Keeping those functions separate reduces the damage if a note or account is ever exposed.
Trust also means checking the original merchant. If a charge looks unfamiliar, I would not immediately label it as fraud or cancel the related subscription from the manager. I would compare the transaction date, search my email receipts, and contact the provider or bank through an official channel. Feenko can help organize the investigation, but it should not replace verification.
Who should try it, and who should skip it
I would recommend trying Feenko to someone who has several recurring services, dislikes complicated budgeting software, and is willing to perform a modest monthly review. It is particularly appealing if the main frustration is uncertainty: not knowing what renews, which services are still active, or how many small commitments have accumulated.
I would be less enthusiastic for a person with an extremely simple financial life. If I have only one subscription and already receive a dependable reminder, the app may add little value. I would also skip it if I want investment tools, detailed cash-flow forecasting, or a complete account aggregation experience. Those needs belong to wider finance categories.
People who dislike manual organization should think carefully before installing. The app can make subscription information easier to review, but I still need to enter, verify, and maintain that information responsibly. If I refuse that small amount of upkeep, a bank alert or calendar reminder may be a better match, even if it offers less overall perspective.
The Everyone rating makes it broadly approachable from an age-classification standpoint, but that should not be confused with financial suitability for children. I would still treat the app as an adult household-money tool and discuss any shared subscriptions with the person responsible for the payment account.
My recommendation after weighing the trade-offs
I see Feenko as a focused decision tool, not a replacement for a bank, a budget, or a cancellation service. Its best use is helping me turn scattered recurring charges into a reviewable list, then giving me the prompt to decide what stays. That is a modest goal, but it addresses a common problem without requiring me to redesign my entire financial life.
The free entry point makes experimentation straightforward, while the optional purchases mean I would inspect the upgrade details before paying. I would begin with a limited trial of my own routine, compare the resulting list with bank activity, and only then decide whether the app deserves a permanent place on my phone.
My final recommendation is positive for subscription-heavy households and cautious users who want a dedicated finance organizer. I would recommend a broader budgeting alternative for anyone seeking complete financial planning, and a calendar or spreadsheet for anyone with very few recurring charges. Choose Feenko when the problem is subscription visibility, not when you need an entire financial command center.
In that role, the app has a clear reason to exist. It can help me notice recurring commitments, prepare better questions about my spending, and make cancellation decisions with less guesswork. The results still depend on my follow-through, but for the right user, that focused structure is exactly what makes it worth trying.
4.4
258.00 Reviews
Pros
- Clear overview of recurring subscriptions and upcoming charges.
- Helps identify unused services and potential savings.
- Useful reminders can reduce missed cancellation dates.
- Simple interface makes subscription tracking easy.
- Supports better control of monthly and yearly spending.
Cons
- Subscription data may require manual entry and regular updates.
- Some features may be restricted to a paid plan.
- Accuracy depends on keeping prices and billing dates current.
- Limited value for users with only a few subscriptions.
- Privacy concerns may arise when entering financial information.


